
Finance Weekly | Fed Hike Bets and a Global Bond Selloff as Canada's Job Market Stumbles
This week's theme: rate hikes resuming and bond markets under strain. After the Fed restarted hiking in September, December hike bets topped 80% and a global bond selloff followed as U.S. yields neared multi-decade highs. U.S. consumer sentiment hit a record second-low; Canada lost 68,000 jobs; the ECB hiked again but French fiscal turmoil clouded its path; China's central bank set out its RMB stance and extended gold buying to 23 months; South Korea lost favor as foreign capital fled.
This week's global financial story was all about "rate hikes resuming and bond markets under strain." After the Federal Reserve restarted hiking in September, markets now assign roughly an 80% or higher probability to another hike in December, U.S. Treasury yields are hovering near multi-decade highs, and a global bond selloff has followed. U.S. consumer sentiment slid to its second-lowest reading on record ahead of the midterms; Canada unexpectedly shed 68,000 jobs in September; the ECB delivered its second hike of the year but France's fiscal and bond-market turmoil clouded its path; China's central bank set out its RMB exchange-rate policy stance and extended its gold-buying streak to 23 months; and South Korea's stock market lost favor as foreign capital fled. Here are this week's ten in-depth observations.
1. Ahead of the Midterms, U.S. Consumer Sentiment Hits a Record Second-Low
Source: CNN
With the midterm elections fast approaching, U.S. consumer sentiment has posted another historically weak reading. The University of Michigan's preliminary consumer sentiment index fell to 46.3 from 48.1 in September; if that reading holds, it would be the second-lowest ever recorded in a survey that dates back 74 years. In other words, Americans now feel worse about the economy than they did during the Vietnam War, the 1970s oil crisis, 9/11, the Great Recession, the Covid-19 pandemic, and the inflation surge that followed. Five of the lowest readings on record have come this year, with May the nadir.
Behind the number is a squeeze from both prices and interest rates. Regular gasoline averages about $4.37 a gallon nationwide, oil has climbed again in recent months, inflation has picked up, and rates have started moving north once more. James Knightley, chief international economist at ING, notes that more than 80% of respondents think it is a bad time to make big purchases — 73% say it is a bad time to buy a household appliance, 78% a vehicle, and 87% a home. Citing Federal Reserve data, he adds that the top 20% of households (earning $155,000 or more) hold more than 70% of U.S. wealth and account for 40% of spending, making the economy markedly "K-shaped."
Impact and trend: Notably, this pessimism diverges from hard economic data — under the "K-shaped" structure, the wealth effect and spending of high-income households are still supporting growth. Knightley warns that a stock-market correction arriving while stress builds elsewhere could genuinely undermine the U.S. growth narrative. For markets, weak sentiment combined with sticky inflation is precisely the argument for the Fed keeping rates high — and it gives this reading extra political significance before the election.
Outlook and risks: Looking ahead, gasoline prices, inflation data and interest-rate direction will determine whether sentiment can recover. If consumers pull back on big-ticket spending out of "should-I-buy" caution, durable-goods and housing demand — key drivers of economic activity — would be first to suffer, which is the risk most worth watching right now.
2. "Higher for Longer" Dominates as December Hike Bets Top 80%
Source: Sina Finance
With little data on the calendar, this week's narrative revolved around uncertainty over Fed policy. Minutes of the Fed's September meeting, released early on October 8, showed "higher for longer" remains the dominant theme: the Fed unanimously voted to raise rates by 25 basis points at its September 15-16 meeting, but policymakers were clearly split on the rationale — some participants worried about energy and other price shocks broadening, while more hawkish core officials saw the hike as necessary to guard against demand-driven inflation.
Key data underscored how sharply expectations swung. On the day the minutes were released, the CME Fed tool showed a 19.4% probability of at least a 25-basis-point hike later this month, down from about 38% a week earlier; yet markets priced an 83% to 85% chance of a hike at the December 8-9 meeting. Against that backdrop, gold swung from losses to gains this week: it opened at $4,142 an ounce on Monday (October 5), touched a fresh low since August 4 of $4,066 on Wednesday, then rebounded to close near $4,195 on Friday, up about 53 points for the week. The dollar rose for a fourth straight week, touching a high since April 2025 of 102.53 intraday on Monday and moving from 101.88 to 102.22 over the week.
Impact and trend: Beyond safe-haven demand, this week's relative gold strength also reflects an "invisible floor" from China's central bank, which keeps adding to its gold reserves — by end-September China held 77.47 million ounces, up 740,000 ounces on the month, a 23rd straight month of increases. Official buying is insensitive to short-term swings, providing important downside support and reflecting a long-term strategy of reserve diversification and hedging against U.S. dollar credit risk.
Outlook and risks: Next week's key variables are U.S. September CPI and a flurry of Fed speeches. On October 13, Fed officials Hammack and Waller will speak, followed by September CPI on the 14th and PPI plus retail sales on the 15th. If inflation comes in above expectations and lifts rate-hike bets further, gold could come under renewed pressure; if inflation cools and yields fall, gold could finally reverse higher. The $4,000 level is the bull-bear dividing line.
3. Dalio Warns the Stock Market's Cushion Against the Bond Selloff Is Wearing Thin
Source: CNBC
Billionaire investor and Bridgewater Associates founder Ray Dalio warned on Thursday that stocks face mounting pressure from rising bond yields and the prospect of weaker corporate cash flows, even as earnings keep growing. Speaking to CNBC at the Milken Institute Asia Summit in Singapore, he said equities have so far weathered the global bond sell-off because earnings growth has kept expected stock returns attractive relative to bonds — but that advantage is narrowing, potentially leaving equities more vulnerable as financial conditions tighten.
Dalio was blunt about where the cycle stands. "We're in the part of the cycle where interest rates can rise without sending the equity market down because there's enough earnings growth and there's enough expected return. But when that cushion comes down, then you're coming later into that cycle. So that's where we are." He warned that as stock prices climb and bond yields rise, that relative advantage is diminishing, credit spreads have already begun to widen, and investors may be overlooking deteriorating corporate free cash flow. "You have to pay attention to free cash flows, not just earnings."
Impact and trend: Dalio's warning lands at a pivotal moment: U.S. Treasury yields hover near multi-decade highs as investors digest large government deficits, persistent inflation and rising borrowing tied to artificial-intelligence investment. He said plainly, "We are in a bond bear market... and there's more to go would be my guess," with the global bond sell-off likely to continue as governments and companies compete for capital. That view poses a direct challenge to richly valued equities.
Outlook and risks: Dalio stopped short of predicting an earnings decline or an imminent correction, saying financial conditions have not yet tightened enough to significantly curb credit and spending. But he stressed that higher borrowing costs will eventually force a reduction in credit and spending, weighing on economic activity and potentially spilling into equities. For investors, this bond-market adjustment is only beginning, and the divergence between earnings and cash flow will be a key window to watch.

4. China's Central Bank Lays Out Its RMB Exchange-Rate Stance: No Preset Target Level
Source: CCTV
On October 8, the People's Bank of China issued a policy statement on the RMB exchange rate, an unusually systematic response to a recent flurry of international commentary on the currency. The central bank stressed that China runs a managed floating exchange-rate regime based on market supply and demand and adjusted with reference to a basket of currencies, letting the market play a decisive role in rate formation, while explicitly stating it does not preset a target level, does not intervene in long-term trends, and maintains exchange-rate flexibility and two-way fluctuation.
A series of figures from the central bank sketches the RMB's steady underpinnings. Over more than two decades the RMB has moved in both directions, and since 2010 it has gone through multiple appreciation and depreciation cycles, trading within a wide 6.04-7.35 range against the dollar, with swings exceeding 10% in each cycle; since 2025 the RMB has appreciated about 9% against the dollar. The central bank also noted that global forex turnover averaged nearly $10 trillion a day in 2025, with the RMB above $800 billion daily and offshore trading accounting for about 80%.
Impact and trend: Responding to voices attributing trade imbalances to exchange rates, the central bank countered that there is no simple linear relationship between the exchange rate and the current account — a surplus does not mean a currency is undervalued, nor a deficit a reason for depreciation — and that as a responsible major country China has never engaged in competitive devaluation. Notably, it stressed that sharp short-term depreciation can destabilize finance and that it will use macro-prudential tools and, in extreme scenarios, direct intervention to correct herd behavior and self-reinforcing irrational depreciation expectations.
Outlook and risks: The central bank said that during the "15th Five-Year Plan" period it will keep transforming its growth model, expand domestic demand, and deepen high-standard opening-up to move the global economy toward a more open, inclusive and balanced direction. For markets, the statement sends a clear signal: amid a faster rise in the dollar index and U.S. Treasury yields, RMB pricing will lean more on market supply and demand, but the bottom line of guarding against short-term disruptive overshooting remains firm.
5. China's Central Bank Buys Gold for a 23rd Straight Month, the Biggest Monthly Add of This Cycle
Source: Caixin
China's gold stockpiling continues. According to the latest official reserve data released by the State Administration of Foreign Exchange on October 7, China held 77.47 million ounces of gold by end-September, up 740,000 ounces on the previous month. The current buying streak has now run 23 months, and the monthly increase was the largest of this cycle, matching October 2023; cumulative additions in this cycle have reached 4.67 million ounces. Foreign-exchange reserves, meanwhile, appeared to "shrink" on paper.
Over a longer horizon, the scale of this strategy is clearer. China's gold reserves are now 2.3 times their level 17 years ago — at end-April 2009, official holdings stood at 33.89 million ounces. The central bank has since conducted four rounds of gold buying, with the previous three rounds adding 5.92 million, 3.40 million and 10.16 million ounces respectively. Steady, consistent official buying stands in stark contrast to the in-and-out flow of short-term speculative money.
Impact and trend: Behind the buying lies a long-term strategy of reserve diversification, hedging U.S. dollar credit risk and responding to geopolitical uncertainty. Even when gold prices tumble, official buying can still provide important downside support. Twenty-three straight months of increases also send a signal: on price pullbacks, gold is still seen as a strategic asset worth holding — one of the structural forces behind gold's resilience this cycle even as U.S. Treasury yields stay high.
Outlook and risks: It is worth noting that official purchases are strategic allocation demand, insensitive to short-term price moves, so they act more as a "floor" than a "lift." If U.S. inflation data turn choppy and rate-hike expectations heat up again, gold could still face short-term pressure; but as long as the two long-term logics of reserve diversification and U.S. debt credit concerns remain, official buying is likely to continue.

6. Where Does the 550 Billion Yuan in Fiscal Stimulus Go? Local Debt Quotas "Reactivated"
Source: CCTV Finance
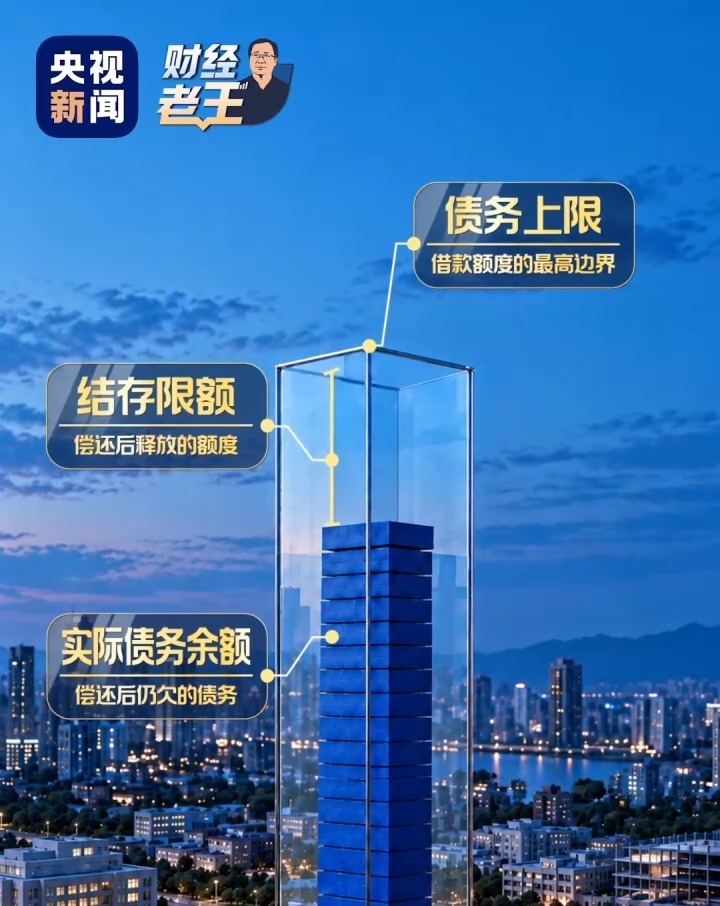
On October 9, the Ministry of Finance released a major piece of good news: it will arrange the use of 550 billion yuan of local-government debt carryover quotas. Where this money comes from and where it goes bears directly on grassroots operations and fourth-quarter investment stabilization. The "carryover quota" refers to the portion of a local government's debt ceiling that sits unused after it repays some debt — this arrangement reactivates that dormant capacity.
The destinations are clearly prioritized. Of the total, 300 billion yuan of general-debt carryover quota will be channeled entirely down to the county and district level, dedicated to strengthening local general public budget capacity; the other 250 billion yuan, from special-debt carryover quota, focuses on construction and investment stabilization — not spread evenly, but directed to regions with real project-funding needs in the fourth quarter, tilted toward major economic provinces, prioritizing projects already under construction, with new projects concentrated in key areas such as the "six networks."
Impact and trend: The elegance of the move is that it "revitalizes stock" rather than "adding new debt." It does not breach the debt-risk bottom line, yet uses incremental funds to protect livelihoods and improve urban and rural public services. For major economic provinces, well-stocked good projects can now get capital injections and quickly translate into physical work, which matters greatly for fourth-quarter growth stabilization. With external rates high and domestic effective credit demand still weak, fiscal policy is absorbing part of the growth-support burden.
Outlook and risks: It is worth noting that total carryover quota is limited, so the effect is more "point-in-time offset" than "trend reversal." Whether it can generate sustainable investment pull still depends on project pipelines and matching funds being in place; if physical work is not formed in time, the backstop for growth could be diluted.
7. Canada Unexpectedly Sheds 68,000 Jobs in September as Unemployment Rises to 6.5%
Source: CBC
Canada's labour market missed badly for a second straight month. Statistics Canada data showed the country lost 68,000 jobs in September, far from economists' forecast of a gain of 9,200, while the unemployment rate rose 0.1 percentage points to 6.5%, back to where it stood at the start of the year. August had already seen a surprise loss of 42,000 jobs. Before the two declines, employment had risen by 181,000 between April and July, and is still up 95,000 year over year.
By sector, losses were concentrated in the public sector, which shed 70,000 roles, with education falling most (concentrated in Quebec), alongside declines in health care and social assistance and manufacturing; the private sector held roughly steady and added a few jobs — a "silver lining" for BMO chief economist Doug Porter. By age, youth aged 15 to 24 accounted for 48,000 job losses, with that group's unemployment rate steady at 13%; core-aged women (25-54) held 28,000 fewer positions. By province, Quebec lost 49,000 and British Columbia 20,000, while Alberta added 23,000.
Impact and trend: This is the Bank of Canada's last look at the labour market before its October 28 rate decision. CIBC senior economist Andrew Grantham argues that despite data volatility, the drop in jobs will likely keep the central bank on hold in the near term; weakness in manufacturing may signal that new tariffs in effect since August are starting to bite. For an economy heavily reliant on housing and consumption, softening employment plus trade-war pressure makes the policy trade-off even thornier.
Outlook and risks: Porter noted that two straight months of job losses of this size are "rare," suggesting the economy was struggling in early fall. Markets had priced in a possible December rate hike, but expectations eased after the weak jobs report. The risk is that if the trade war keeps eroding employment while energy-driven inflation stays elevated, the Bank of Canada will face an even harder choice between stabilizing growth and controlling inflation.

8. Bond Yields Are Already Repricing Canada's Fixed Mortgage Market
Source: Mortgage Professional America
Canadian mortgage borrowers are already paying for a decision the central bank has yet to make. Over the past month, five-year Government of Canada bond yields have climbed 20 basis points, and anyone renewing or initiating a fixed-rate loan today is absorbing costs the Bank of Canada has not formally set. The driver is a global bond sell-off, and the Federal Reserve's FOMC raised rates by 25 basis points at its September meeting.
The key difference between Canada and the U.S. is the starting point. RBC economist Claire Fan put it directly on the RBC Economics podcast The 10-Minute Take: "The key difference here is that Canada's economy is starting from a really relatively softer spot." She noted there is still slack in the Canadian economy by many measures, and with slack persisting in the labour market, businesses have less capacity to pass cost pressures on to consumers — giving the central bank more flexibility than the Fed when weighing inflation trade-offs.
Impact and trend: Fan stressed that for most households, why bond yields are rising simply does not matter — it matters that they are. Fixed- and floating-rate borrowers diverge: the former are hit immediately, while the latter are insulated until the central bank acts. Because fixed-rate mortgages make up the majority of Canadian household borrowing, any household rolling over or renewing — say, renewing a five-year fixed-rate mortgage — is likely already feeling the squeeze from higher yields, even before the central bank delivers the hikes that drove them.
Outlook and risks: Canada's federal debt-to-GDP ratio is roughly half that of the United States and is expected to trend sideways. Fan said that could yet drive divergence in bond yields between the two countries. But that divergence is still developing and borrowers cannot wait — in the current environment, upward pressure on fixed mortgage costs is unlikely to fade in the near term.
9. Alarm Bells in the French Bond Market: Borrowing Costs Near 25-Year Highs, Why Isn't the ECB Intervening?
Source: ProtoThema
France is facing intense sell-offs in its government bond market, with borrowing costs approaching their highest levels in 25 years. Since early September, the yield on France's 10-year government bond has risen by about 80 basis points, approaching 5% — a level not seen since July 2002. A high fiscal deficit, plus political uncertainty ahead of the spring 2027 presidential election, is making investors increasingly cautious; the yield rise in turn adds to the burden on public finances by raising the cost of servicing and refinancing the debt.
Eurozone finance ministers and the ECB appear reluctant to intervene. At their monthly meeting in Luxembourg on Thursday, October 8, eurozone finance ministers urged Paris to accelerate passing a new budget to reduce uncertainty around the fiscal trajectory of the EU's second-largest economy. Afterward, European Commission Executive Vice-President Valdis Dombrovskis, responsible for economic affairs, stressed the need for prudent fiscal policy, especially among high-deficit and high-debt countries, and said he was in contact with French Finance Minister Roland Lescure, calling credible budget planning a key prerequisite for restoring predictability.
Impact and trend: The French bond turmoil throws into relief the tension in the eurozone between fiscal discipline and market stability. Facing surging borrowing costs, eurozone finance ministers and the ECB have both appeared reluctant to intervene, making clear that restoring market confidence is primarily the French government's own responsibility; European Commission Executive Vice-President Dombrovskis urged "prudent fiscal policy," singling out high-deficit, high-debt countries. That means until France delivers a credible budget, the ECB is likely to rely mainly on verbal guidance rather than readily deploying tools to intervene directly in the bond market.
Outlook and risks: The key variable is whether France can deliver a credible 2027 budget. If the budget drags on and yields keep climbing, a negative feedback loop between fiscal and political risk could intensify and spill over into broader eurozone assets; conversely, if the budget process speeds up and market confidence recovers, pressure on the eurozone bond market could ease. Either way, France has become the storm center for watching the eurozone's fiscal-versus-monetary policy tug-of-war.
10. South Korea's Stock Market Loses Favor: Over 87 Billion Yuan of Foreign Capital Exits in 2026, Samsung's Foreign Stake Hits an 18-Year Low
Source: 21st Century Business Herald
South Korea's stock market, for much of the year the poster child of the global AI trade, is rapidly losing investor attention. Bloomberg reported on the 11th that Korean market turnover has plunged 70% from its late-May peak, foreign investors are exiting quickly, and local retail investors are also pulling back. The Kospi, the world's best-performing major index in the first half, has since fallen 22%, becoming the worst performer in the second half, even as U.S. stocks, similarly heavy in AI, hit new highs.
The root of the reversal is the market's over-reliance on two memory-chip giants, Samsung Electronics and SK Hynix. Bloomberg-compiled exchange data show foreign money withdrew $131 billion (about 876.68 billion yuan) from Korean stocks this year, the most among major Asian markets, while the two chipmakers together account for more than half of the Kospi's weighting. Even though Samsung's third-quarter operating profit hit a record 107 trillion won, its shares fell on Thursday, underscoring doubts about the durability of memory-chip demand. According to Yonhap, foreign investors' stake in Samsung stood at 46.38% as of October 8 — the lowest since 46.35% on January 11, 2008, a gap of about 18 years and 9 months — while SK Hynix's foreign holding fell to 49.59%, below 50%.
Impact and trend: Investors are voting with their feet and re-pricing the sustainability of the memory-chip boom. Phillip Wool, head of portfolio management at Rayliant Global Advisors, said the "easy money" in the theme has already been made for most investors; his fund has been taking profits on Korean AI stocks and is underweight Samsung and SK Hynix. Richard Tang, head of research in Hong Kong at Julius Baer, noted capital is increasingly shifting to U.S. stocks, driving continued outflows from Korea. J.P. Morgan says the nearing completion of the two chipmakers' combined 55 trillion won of buybacks could make the outflow problem more acute.
Outlook and risks: Not everyone is bearish. Citi's Peter Lee recommends investors start buying Samsung and SK Hynix, arguing the market underestimates how much HBM chips will be needed in 2027. But Lee Jaewon, a researcher at Yuanta Securities' Korea branch, cautions that "outstanding results alone are unlikely to reverse foreign flows." The Kospi's low valuation — the so-called "Korea discount" — is both a risk and a potential value-recovery opportunity; the key still hinges on the memory cycle and global risk appetite.
More News
- Maple Express | October 11, 2026 — Toronto Community Honours 8-Year-Old Boy Killed by Stray Bullet
- Global Express | October 11, 2026: Houthi Attack on Riyadh Airport Kills 12 as World Condemns
- Tech Express | October 11, 2026: Claude Filed a Fake Homicide Tip, Prompting New US AI Safety Reporting Rules
- Sports Express | October 11, 2026 — Guardians set postseason strikeout record, rally past White Sox into ALCS
- Maple Express | October 10, 2026 — Toronto food banks see record demand as mayoral candidates join Thanksgiving food sort
Comments (0)
View More
 -65%
Turtle Beach Kone XP Air Wireless Gaming Mouse — 19,000 DPI, 29 Buttons, Charging Dock! $59.99 CAD (65% Off)
 -36%
Anker soundcore 2 Portable Bluetooth Speaker — IPX7 Waterproof, 24H Playtime, 146K Ratings! $44.99 CAD (36% Off)
 -16%
Marvel's Spider-Man: Miles Morales Ultimate Edition (PS5) — Sony's Acclaimed Exclusive! $74.99 CAD (16% Off)
 0
「Worth It」STANLEY IceFlow Flip Straw Tumbler 30oz — 7h Cold, 35h Iced!
 Sports Express
 | October 11, 2026 — Guardians set postseason strikeout record, rally past White Sox into ALCS
Finance WeeklyFinance Weekly | Fed Hike Bets and a Global Bond Selloff as Canada's Job Market Stumbles
-65%Turtle Beach Kone XP Air Wireless Gaming Mouse — 19,000 DPI, 29 Buttons, Charging Dock! $59.99 CAD (65% Off)
Best Buy
-36%Anker soundcore 2 Portable Bluetooth Speaker — IPX7 Waterproof, 24H Playtime, 146K Ratings! $44.99 CAD (36% Off)
Amazon
-16%Marvel's Spider-Man: Miles Morales Ultimate Edition (PS5) — Sony's Acclaimed Exclusive! $74.99 CAD (16% Off)
Amazon
0「Worth It」STANLEY IceFlow Flip Straw Tumbler 30oz — 7h Cold, 35h Iced!
Amazon
Sports ExpressSports Express | October 11, 2026 — Guardians set postseason strikeout record, rally past White Sox into ALCS
Finance Weekly