
Finance Weekly | The AI Trade Cools as Rate Hikes Return, and Global Money Reprices Risk
Two themes turned at once this week. The Nasdaq posted its worst month since March 2025 and Alphabet lost half a trillion dollars in a session as the AI trade moved into a 'show me' phase on cash flow. The Fed held but shut the door on easing and cut its meeting frequency; the Bank of Canada hiked to 2.5% for the first time in three years; the ECB paused as French bond yields did the tightening. China created a bond-liquidity backstop and called a buyback-relending meeting.
The Week in Brief
Two themes turned at once this week. The AI trade that powered markets for two years faced its first systemic test: the Nasdaq posted its worst month since March 2025 and Alphabet shed half a trillion dollars of market value in a single session. At the same time, rate hikes returned to the table — the Federal Reserve held but closed the door on easing, the Bank of Canada raised for the first time in three years, and the Bank of Japan accelerated its ETF sales. China moved on two fronts, creating a bond-market liquidity backstop for non-bank asset managers and calling a Monday meeting to refine its buyback relending programme. Money made its choice: out of expensive tech, into long-duration government bonds.
1. Three regulators meet Monday to refine buyback relending
Source: Lianhe Zaobao
On November 1, Cailianshe reported, citing industry sources, that the People's Bank of China, the National Financial Regulatory Administration and the China Securities Regulatory Commission will summon major banks to a meeting on Monday, November 2, to discuss refining the relending facility for share buybacks and shareholder increases. On the same day, the central bank and the securities regulator will hold a separate meeting to promote the use of capital-market support tools; some brokerages and fund companies have already been notified. The news landed while Chinese equities remain under sustained pressure.
The facility is not new. In October 2024 the PBOC created the buyback and increase relending programme with an initial quota of 300 billion yuan, channelling bank loans to listed companies and major shareholders for repurchases and stake increases. Two years on, the policy has entered a "refinement" phase — an acknowledgement that disbursement has fallen short of market expectations.
The pressure comes from two directions. Bloomberg data show the CSI 300 fell 8.5% in October, its 12th consecutive weekly decline and the longest losing streak on record, with the global selloff in AI-related stocks further weighing on risk appetite. On the real economy side, the October manufacturing PMI fell to 49.3 and the non-manufacturing business activity index to 49.7, both into contraction.
Read together, the purpose of Monday's meeting is not hard to infer: support the index with market-based tools without letting policy be read as an unconditional backstop. Whether the meeting yields additional quota or looser eligibility will determine how far the early-November mood recovery can run.
2. The PBOC creates BNSF, an emergency channel for non-bank managers
Source: 21st Century Business Herald
On October 26 the People's Bank of China formally established the Bond Market NBFI Swap Facility (BNSF), an emergency funding channel aimed at bank wealth-management subsidiaries and public fund managers. It is designed to be used only in extreme conditions — when the bond market swings sharply and asset-management products face concentrated redemptions.
The need reflects the size of the industry. At the end of 2025, outstanding wealth-management products reached 33.29 trillion yuan and public fund net assets about 37.71 trillion yuan — more than 70 trillion yuan combined, with a large share allocated to bonds. Banks have long been able to borrow from the central bank through reverse repos, the medium-term lending facility and standing lending facility; non-bank managers facing a liquidity shock had no mature mechanism.
According to 21st Century Business Herald, the tool borrows from the design of the October 2024 swap facility for securities firms, funds and insurers: asset managers borrow central bank bills from the PBOC for repo funding, using the proceeds to buy qualified assets of products hit by large redemptions. Parent banks and parent securities companies are also eligible counterparties, given their stronger balance sheets. Governor Pan Gongsheng previewed the design at the 2026 Financial Street Forum.
The operative principle is "emergency relief, not a bailout." The PBOC requires participating institutions to keep meeting prudential requirements throughout, and Pan stressed macro-prudential conditions and high-grade collateral to prevent distorted pricing and the illusion of a backstop. Zhang Xu, chief fixed-income analyst at Everbright Securities, said the prudential requirements apply for the entire period of use and that losses from excessive speculation should not be shifted to others. That boundary makes BNSF a stabiliser, not a rescue fund.
3. As equities enter a bear market, 13.8 billion yuan flows into 30-year bond ETFs
Source: Lianhe Zaobao
Chinese equities fell into a bear market in October, and investors voted with their money. Bloomberg-compiled data show two onshore ETFs tracking 30-year government bonds took in a combined 13.8 billion yuan in October, the most since July 2025. The inflows pushed both funds to record market values: since the start of the second half, the Pengyang ChinaBond 30-Year Treasury ETF has grown 57% and the Boshi SSE 30-Year Treasury ETF 68%.
Three forces support the bond market: modest growth, ample liquidity and a lack of attractive alternatives for onshore investors. By contrast, weak consumption and deepening doubts about AI profitability pushed Chinese equities into a bear market, making them among the world's worst performers.
The curve has shifted lower across the board. ChinaBond data show five- and seven-year yields closed at record lows on October 29; the 10-year yield sits at 1.62%, only a few basis points above the record low touched in early 2025. The 30-year yield is around 2.05%. Liao Zhiming, an analyst at Huayuan Securities, expects falling funding costs and reduced supply to pull the 30-year yield to about 2% by year-end. Open interest in 30-year bond futures has hit a record as hedge funds pile in.
Jeffrey Zhang, a strategist at Credit Agricole in Hong Kong, said relatively loose liquidity will keep supporting bond demand, and noted that Chinese bank stocks outperforming the broader market reflects strong appetite for fixed-income-like assets. The risk is crowding: once haven flows press long yields to historic lows, any stabilisation in equities or pickup in supply could produce an equally fast reversal.
4. The Fed holds rates — and changes how often it meets
Source: Caixin, Xinhua
On October 28 the Federal Reserve left rates unchanged, keeping the federal funds target range at 3.75% to 4%, in line with expectations. The vote was not unanimous: the FOMC decided 10 to 2, with Fed Governor Cook and Cleveland Fed President Beth M. Hammack dissenting in favour of a 25 basis point hike at this meeting. In September the committee had just delivered a quarter-point increase.
The language shifted as well. The October statement described US economic activity as expanding "strongly," compared with "moderately" in September, with the rest of the statement broadly unchanged — a hawkish signal for a market still watching sticky inflation.
The bigger surprise was institutional. Chair Kevin Warsh announced at his press conference the same day that the committee will gradually reduce the frequency of policy meetings from 2027 through 2028: it will still hold eight monetary policy meetings a year, but in 2027 one meeting will focus on broad monetary policy strategy without voting on the funds rate and without issuing a policy statement; in 2028 there will be two such meetings. The new schedule takes effect next autumn. Warsh was sworn in on May 22 and announced five independent working groups on June 17 to advance his reform agenda.
This is a contraction of the communication framework, not a change in policy direction. The real test comes in December: with the economic assessment upgraded from "moderate" to "strong" and two committee members already arguing for further hikes, holding is a pause, not a pivot. With fewer meetings, each one carries more informational weight — and market moves may become more concentrated, not less.
5. US third-quarter GDP grows 3.4%, with inflation as the price
Source: ABC News
US gross domestic product expanded at a 3.4% annualised rate in the three months through September, according to the Commerce Department's advance estimate released October 29, beating economists' expectations of 3.1%. That marked an acceleration from 2.2% in the second quarter and outpaced the 2.5% recorded in the first quarter. It was the last full economic snapshot before the midterm elections.
Growth was driven mainly by consumer spending and faster investment. Consumption, about two-thirds of the economy, rose at a solid pace even as prices climbed. A jump in artificial intelligence spending had already boosted output in prior quarters, with the largest companies pouring money into chips and data centres.
AI cuts both ways in the GDP maths. Tech firms imported large volumes of critical semiconductors, and the GDP formula subtracts imports to exclude foreign production, which pushed the headline figure down. The harder the AI investment, the larger the import drag on measured growth.
The concern is prices. Inflation surged after the Iran war began in late February, and a key long-term Treasury rate has jumped in recent months as investors feared price increases would erode returns, pushing up credit card and mortgage rates and threatening household finances. Hiring continues to grow, though more slowly, and unemployment remains low by historical standards.
That leaves the Fed in a bind: growth does not need rescuing, but inflation does not permit easing. Market pricing for a December hike rests on exactly that combination.
6. Nasdaq's worst month in over a year: the AI trade enters its "show me" phase
Source: CNN
Wall Street suffered a steep day of losses on Friday, October 30. The Nasdaq Composite dropped 2.86% and the S&P 500 fell 1.82%, each their worst day since June; the Dow fell 572 points, or roughly 1.1%.
Only weeks earlier, the Nasdaq and S&P 500 had clinched record highs. October's reversal came from three overlapping pressures: higher rate expectations, tech companies burning cash on enormous AI spending, and weaker-than-expected earnings and guidance. The Nasdaq is now 7.8% below its record high and suffered its worst monthly decline since March 2025; the S&P 500 is about 3% off its peak.
At the stock level the damage was stark. Intel plunged 28.58%, its worst day since 1974, after issuing weak fourth-quarter guidance and citing higher memory chip costs hurting PC demand. Alphabet fell more than 12% on Thursday, wiping half a trillion dollars off its market value, then lost another 1.4% on Friday to cap its worst month on record. Nvidia fell 4.2%, a closely watched chipmaker index sank 7.2% and Amazon dropped 1.4%.
The real change is in the valuation logic. Alphabet posted two consecutive quarters of negative free cash flow for the first time on record; Meta disclosed its first negative free cash flow quarter since 2012; Amazon reported negative free cash flow of $42.4 billion over the past 12 months. Joe Tigay of Equity Armor Investments said the AI trade is moving "out of the hopes and dreams phase... into the 'show me' phase." Neil Wilson of Saxo Markets put it more bluntly: investors do not just want capex, they want returns already delivered.
7. Bank of Canada's first hike in three years: what comes after 2.5%
Source: Global News
On October 28 the Bank of Canada raised its benchmark rate by 25 basis points to 2.5%, its first increase in more than three years, moving to get ahead of looming price increases.
Inflation was the trigger. CPI rose 3.1% year over year in September, which the central bank largely attributed to high gas prices. It now expects inflation to reach 3.5% at the end of this year before easing to around 2% by mid-2028, with food inflation averaging about 4% in 2027 — roughly half a percentage point above this year.
The household impact is measurable. Lara Stilin, chief financial officer at Your Neighbourhood Credit Union, told Global News that a consumer holding about C$200,000 in a variable-rate mortgage or home equity line of credit will feel about C$500 in additional annual interest. Her concern is more specific: for households that have already stopped eating out, postponed big purchases and dipped into savings yet still come up short, another hike is not about cutting one more item — it is about deciding which bill gets paid this month.
Governor Tiff Macklem said inflation is likely to be "more persistent" and that "there could be a need to raise the policy rate further, but given the uncertainties, we will proceed carefully," taking decisions "one meeting at a time." Charles St-Arnaud, chief economist at Servus Credit Union, expects back-to-back hikes to end the year at 2.75%.
For mortgage holders the question is not this quarter point but whether it is the first of many, the first of a few, or the first and last. The answer depends on oil — and on how much a stalled Canadian economy can absorb.
8. Canada's economy stalls for a second month, with a September contraction likely
Source: CBC
Canada's economic growth stalled in August for the second month in a row, Statistics Canada reported on October 30, and a decline may be coming in September. Real GDP was effectively unchanged for the month after relatively flat growth in July; economists polled by Reuters had expected 0.2% growth. The agency's early estimate for September points to a 0.1% decline.
The drag came from wholesale trade and the public sector. Wholesale trade fell 1.4% in August as most subsectors contracted, with motor vehicle and parts wholesalers shrinking for the first time in seven months as car manufacturing slid and fewer passenger vehicles were imported. Public sector activity also declined, with government public administration contributing most of the drop as work on the 2026 census wrapped up. Mining, quarrying and oil and gas were flat, as higher mining activity was offset by lower oil and gas output from maintenance at some facilities.

Retail trade was a bright spot, up 1.2% and more than making up for July's decline. Manufacturing rose for the fifth time in seven months, and transportation and warehousing as well as finance and insurance gained.
Taken together, the trend is weak. The agency's flash estimate has real GDP expanding 1.3% annualised in the third quarter — down from 3.3% in the second and below the 2% the Bank of Canada projected in its monetary policy report. BMO chief economist Doug Porter said the momentum that appeared to build in the spring is gone — the very resilience the central bank cited at length when it raised rates this week.
CIBC economist Andrew Grantham said the release supports the bank holding fire on a further hike in December. The Bank of Canada framed Wednesday's move as pre-emptive; if that reading holds, the coming data will decide whether this was a one-off or the start of a hiking cycle.
9. The ECB holds, and Lagarde leaves nine months early
Source: Euronews
On October 29 the European Central Bank left its key deposit rate unchanged at 2.5%, with the main refinancing rate at 2.65% and the marginal lending facility at 2.90%. The pause was widely expected, but the meeting was overshadowed by President Christine Lagarde's announcement earlier in the day that she will step down on 7 February 2027, about nine months before her eight-year term ends.
The hold sits between two problems. Eurozone inflation rose to 3.8% in September from 3.2% in August, almost double the 2% target, while a selloff in French government bonds pushed up borrowing costs across the bloc. The ECB has raised rates twice this year, most recently in September, driven by energy prices linked to the Iran war. Its statement said energy prices had "continued to rise, posing upside risks to the inflation outlook and downside risks to the growth outlook," and acknowledged financing conditions "have tightened" since the last meeting.
Lagarde's exit opens a succession race. Spain's Pablo Hernández de Cos and the Netherlands' Klaas Knot are seen as frontrunners, and two other seats on the six-member Executive Board — including chief economist Philip Lane's — open in the first half of next year. Reports have linked the timing to France's presidential election in April 2027.
France is the biggest variable. French 10-year borrowing costs climbed above 5% last week for the first time since 2002 and stood near 5% on Thursday, with the spread over German debt at roughly 155 basis points. Moody's kept France's Aa3 rating unchanged but with a negative outlook. ING estimated the rise in yields since September has done the work of a 25 basis point hike in Germany and closer to 50 in France: "The bond market has taken over the ECB's job."
10. Goldman cuts its target by 25% as Korea's KOSPI falls more than 35% from its peak
Source: Sina Finance
On October 26 the KOSPI fell below 5,500, a closing low in about seven months, as foreign investors net sold nearly 700 billion won that day. Four months earlier, on June 19, the index had touched a record 9,385.59 — a decline of more than 35% from that peak to below 5,500.
The drama is that the slide came during the best earnings in memory. On October 28, SK Hynix's preliminary third-quarter results showed operating profit above 83 trillion won, up 632.1% year on year and a record; revenue reached 104.6 trillion won, up 327.9%. On October 29, Samsung Electronics reported third-quarter operating profit of 107.44 trillion won, up 783%, on revenue of 195.25 trillion won, up 127%, also a record. Neither result lifted the index: on the last trading day of October the KOSPI opened sharply lower, fell as much as 5%, triggered a circuit breaker and still closed down 3.48%.
The turn among investment banks is telling. Goldman Sachs began the year targeting 6,400 for end-2026, raised it to 7,000 in March, lifted its 12-month target to 9,000 in May and to 12,000 on June 3. It reaffirmed that call on August 13 and October 16. Only on October 26 did it cut the 12-month target from 12,000 to 9,000 — a 25% reduction — citing risk-averse trading and concern over memory that has spilt over into the whole market.
Fundamentals have not broken. September exports rose 104.9% year on year on a working-day-adjusted basis to a record $120.9 billion, chip exports surged 263% to $60.3 billion, and third-quarter GDP grew 1.0% quarter on quarter, faster than the 0.6% in the second. Korean academic Kim Yoon-jun argues the decline simply reflects inflated valuations: Goldman has not gone bearish, it has lowered how bullish it is.
The week in conclusion: five central banks tightened the easing narrative almost simultaneously — the Fed paused without loosening, Canada hiked, the ECB held while its bond market did the tightening, the Bank of Japan accelerated ETF sales, and China used liquidity tools to steady bonds and meetings to steady equities. The AI pullback is not a demand collapse; it is a valuation regime that now demands cash-flow proof. Three things to watch: policy expectations after the November 3 US midterms, the December Fed and Bank of Canada meetings, and whether China's November 2 meeting delivers new tools.
More News
- Global Express | November 1, 2026: Iran's Supreme Leader Orders Response 'Without Geographic Limits' as US Standoff Persists
- Tech Express | Nov 1, 2026 — OpenAI Merges ChatGPT and Codex Quotas
- Sports Express | November 1, 2026 Valkyries beat Dream 68-63 to win first WNBA title
- Maple Express | November 1, 2026: Woman dies after stabbing in North York parking lot
- Maple Express | October 31, 2026: Four dead, two seriously hurt in crash near Guelph
Comments (0)
View More
 -27%
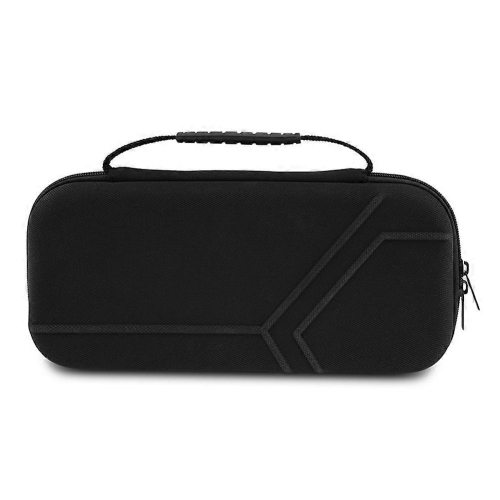
SLOWMOOSE Carrying Case for Nintendo Switch 2 — 12 Game Card Slots & Hard Shell! $30.99 CAD (26% Off)
 -41%
Command Electronics 12V LED RV Clearance Lights (2-Pack) — OEM fit, made in USA! $21.40 CAD (40% Off)
 0
Worth Buying: Airthings Wave Radon Detector — Continuous Monitoring, No Lab Fees, Nothing to Mail In! $199 CAD
 0
Worth Buying: Cottonelle GentlePlus Flushable Wipes — 8 packs, 336 wipes, $17.98 CAD
 Global Express
 | November 1, 2026: Iran's Supreme Leader Orders Response 'Without Geographic Limits' as US Standoff Persists
 Tech Express
 | Nov 1, 2026 — OpenAI Merges ChatGPT and Codex Quotas
-27%SLOWMOOSE Carrying Case for Nintendo Switch 2 — 12 Game Card Slots & Hard Shell! $30.99 CAD (26% Off)
Best Buy
-41%Command Electronics 12V LED RV Clearance Lights (2-Pack) — OEM fit, made in USA! $21.40 CAD (40% Off)
Amazon
0Worth Buying: Airthings Wave Radon Detector — Continuous Monitoring, No Lab Fees, Nothing to Mail In! $199 CAD
Amazon
0Worth Buying: Cottonelle GentlePlus Flushable Wipes — 8 packs, 336 wipes, $17.98 CAD
Amazon
Global ExpressGlobal Express | November 1, 2026: Iran's Supreme Leader Orders Response 'Without Geographic Limits' as US Standoff Persists
Tech Express